Uganda will likely face the highest fuel prices since the civil wars over the next six months, just before it produces oil commercially for the first time.
This is mostly fact. I have been modeling a forecast series as part of continuous work in the oil and gas sector. It is mostly housekeeping at this point meant to anticipate some movements in the sector which is quite busy this season.
So what I can share is this. There is a 60 per cent chance of petrol prices passing Ush7,000 a litre at major Kampala outlets before the end of March next year and a 70 per cent chance diesel does the same. Petrol has averaged UGX 6,529 in August and diesel UGx 6,647. It looks like the needle will move slightly forward with petrol at UGX 6,750 to UGX 7,100 and diesel at UGX 6,950 to UGX 7,350 by the Christmas and New Year.
Much of this is modeled on the uptick in the international oil prices and the factors driving their volatility. Brent settled at $105.68 on September 14 having traded at $71.57 as recently as July 1. It seems likely that this base crude price will average at $98 to $108 a barrel in the final quarter of 2026 and $88 to $100 in the first quarter of 2027. Some analysis suggests that the volatility in the Gulf may further deteriorate with a 55 per cent probability of another disruptive attack on Gulf export or processing infrastructure before the end of March next year.
Well of course it could reverse but the news this year shows a pattern not of a return to the pre-February days (my gosh) but rather a hurtling towards new dangers without an international settlement effort to calm things down. In fact quite the opposite.
I was in Kikuube a few weeks ago for the unveiling of Pearl Sweet and also followed its introduction at the Asian oil conference (APPEC in Singapore)
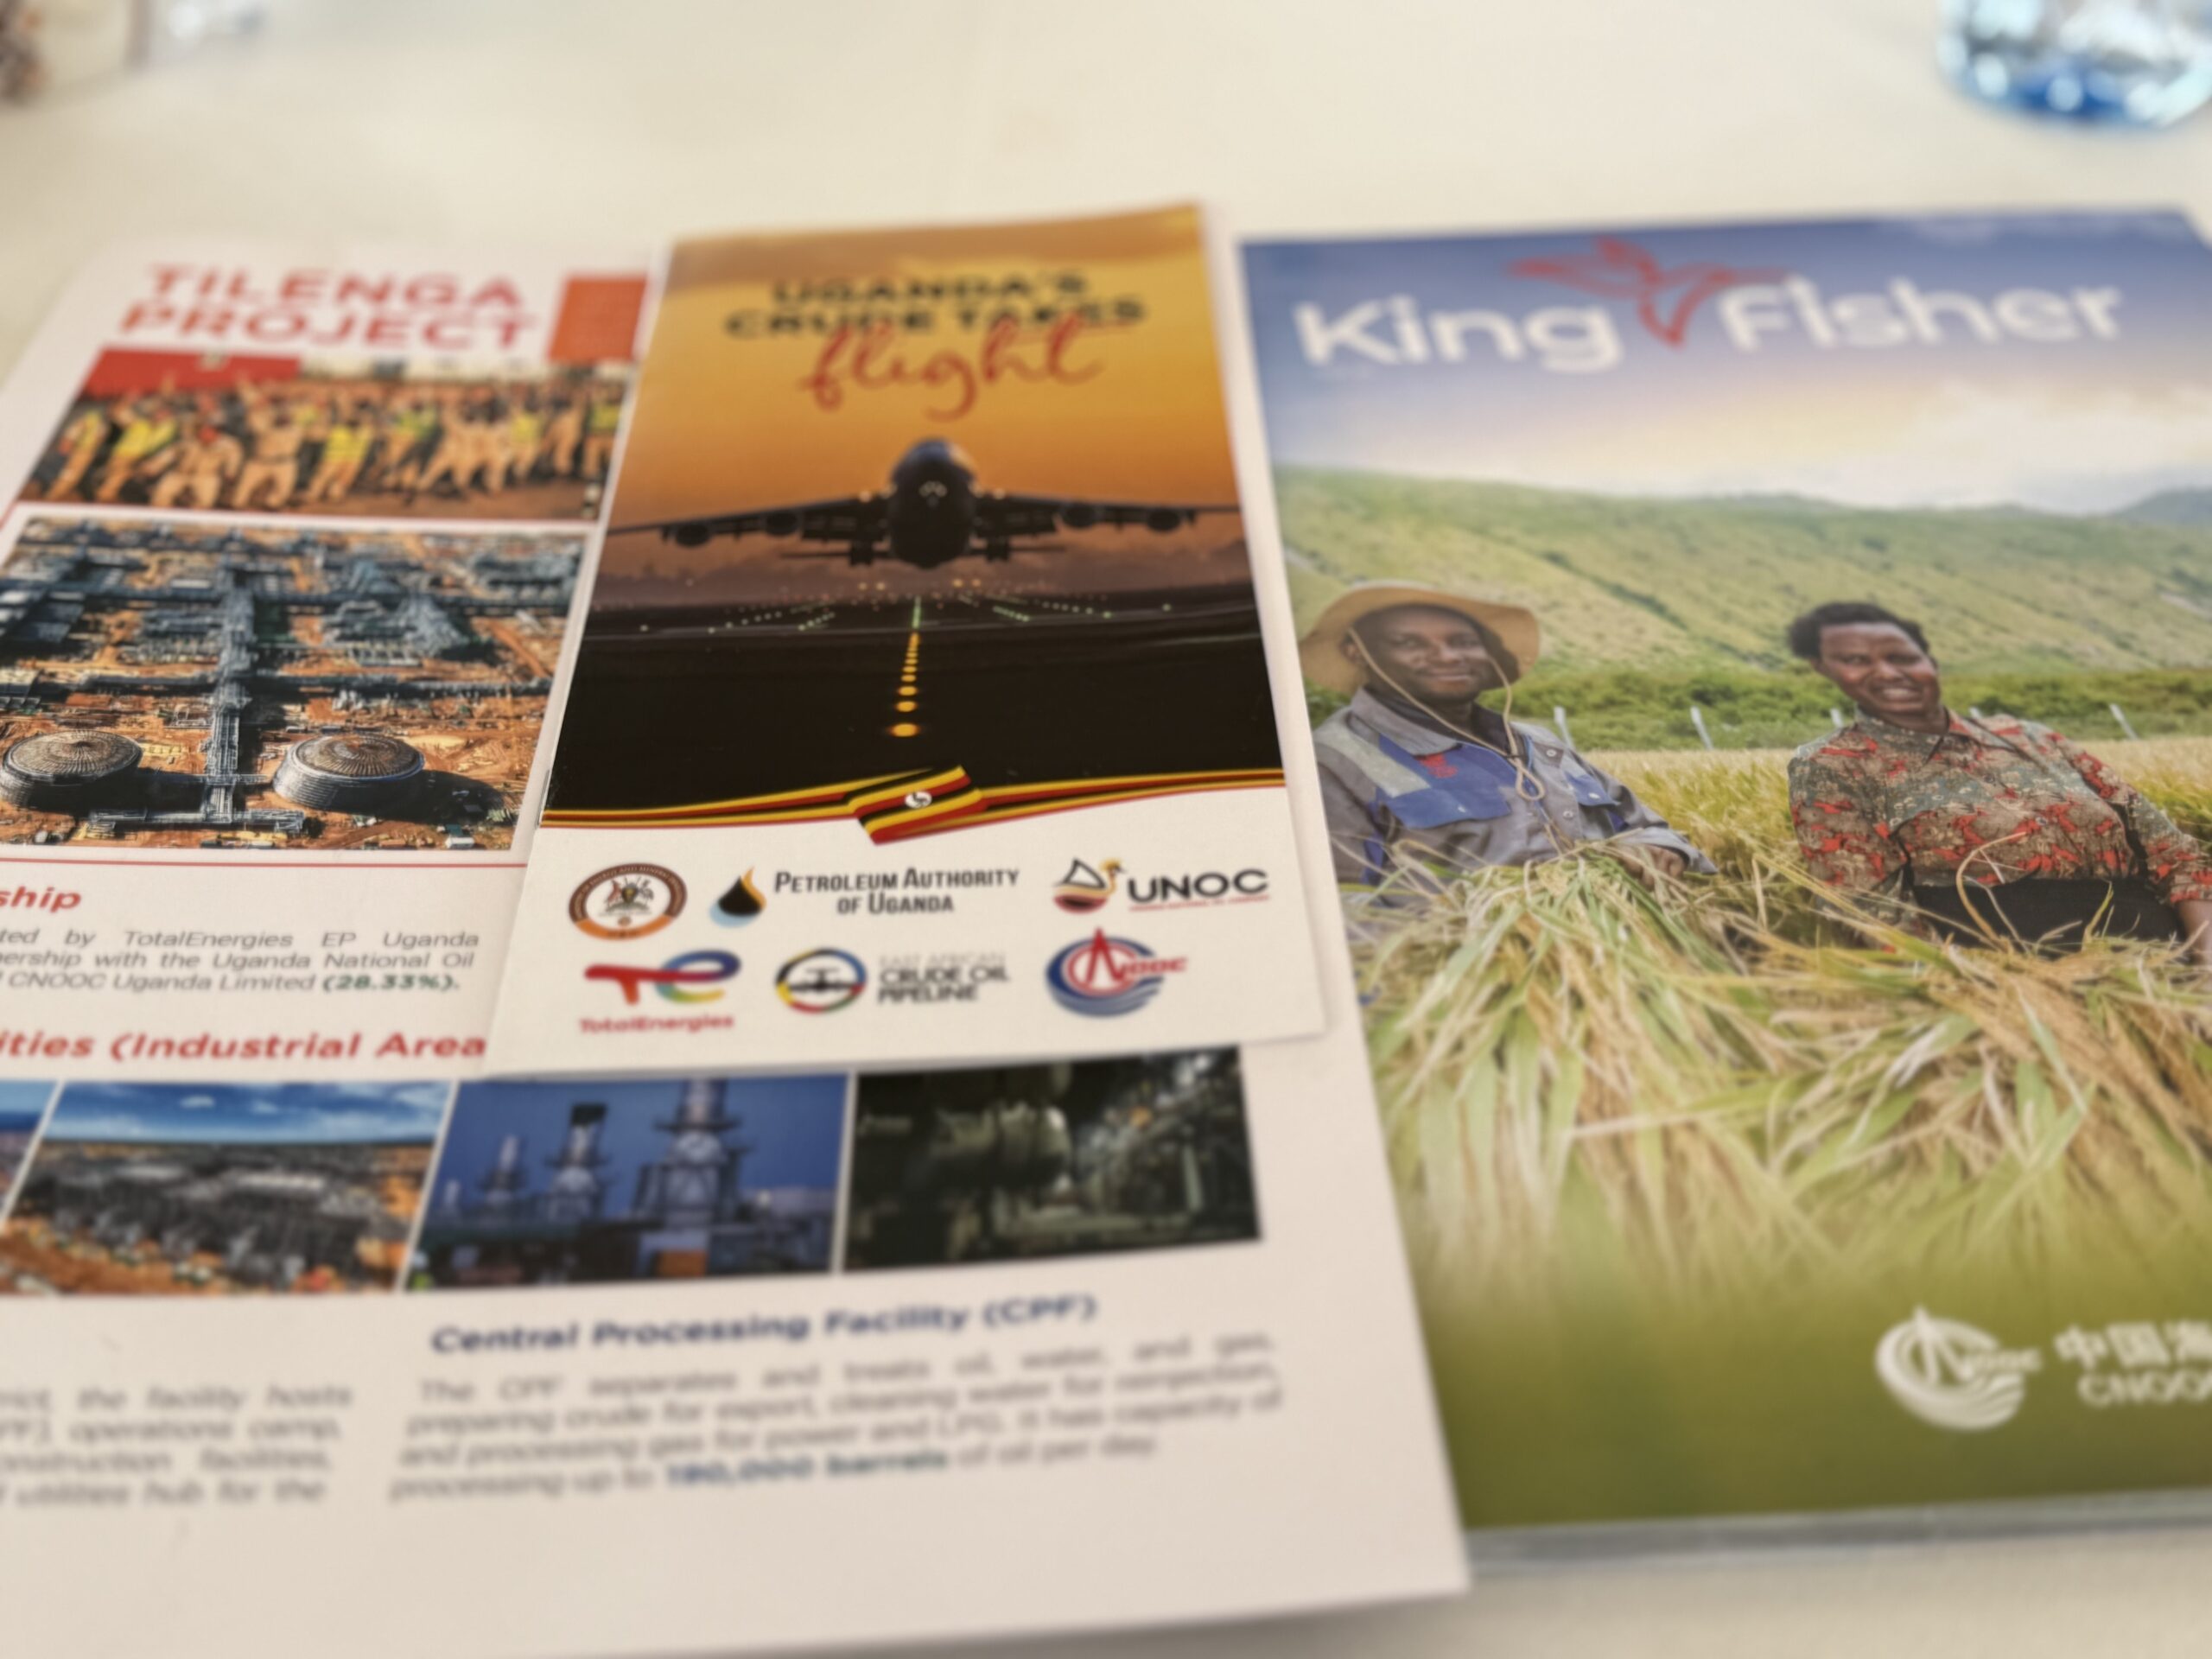
My sense now is that Uganda’s first commercial oil in the second or third quarter of 2027. This is based on the way the Lake Albert oil project has been built to function not anything else. Kingfisher (nearly all complete and ready to supply oil to the pipeline) and Tilenga have separate processing plants and feeder lines. However, at Kabaale their crude shall be metered and commingled into Pearl Sweet before entering EACOP. This is the best commercial proposition according to engineers and policy folks.
Kingfisher crude is particularly waxy. Its reported wax content is 31.2 per cent and its pour point 42-45°C. Tilenga which supplies the larger volume and a less waxy component of the blend is needed for the alchemy to become Pearl Sweet. Together the fields are expected to produce about 230,000 barrels a day at plateau which is literally the number on the Pearl Sweet prospectus. Tilenga and Kingfisher are needed to supply the export blend and EACOP has to be commissioned, filled and heated for the volumes to travel the 1,443km to Tanga. Currently I understand that there is some hydrotesting (running water through the pipeline) to test its functionality but before commercial supplies- the oil testing will be done, and it looks more likely in the second or third quarter.
TIGHTENING OUR BELTS
UNOC, the single import model, that has been incredibly stable throughout this period, depends on forward cargoes. This simply means that the current fuel price is calibrated on petroleum prices of 3-months ago. This is what protected consumers during the first stage of the oil price rises earlier this year. UNOC already had stock purchased when the war in Iran commenced. However even if the Gulf conflict eases this November, I expect Ugandan pump prices to remain close to their peak in March because orders will have been made on the current elevated oil prices.
The import model has meant Uganda kept itself supplied. This is good and there is probably a 75 per cent probability of avoiding a national fuel stockout through March despite the severe conditions on primary sources like the Gulf. Diversification, likely what UNOC and its partner Vitol have pivoted too is however expensive. When Gulf product is constrained, cargoes can be bought from West Africa, Europe and the US Gulf. Those journeys are however longer and pricier, particularly while Suez and Bab al-Mandab remain disrupted, but they provide alternatives.
Here Uganda is looking ahead to future stability. President Museveni today (September 17th) commissioned new storage facilities (UNOC is developing a 320mn-litre Kampala Storage Terminal at Namwabula in Mpigi. Jinja is being expanded from 30mn to 40mn litres and UNOC is in the final stages of acquiring a 110mn-litre terminal at Mombasa. Namwabula is ultimately intended to receive refined products from Hoima through a 211km pipeline). Expanded storage will in the future give some headroom to deal with both supply and cost when disruptions happen. I am not being pessimistic but a return to pre-Iran war stability shall not happen within the window where Uganda is a commercial oil producer. The other issue I have been banging on for years, a domestic refinery, is the only real solution to insulate Uganda from the risks of disruption we are seeing around the world today.
Every UGX 1,000 added to the average price of a litre of petroleum represents roughly UGX 240 bn a month across national demand. Against early-2026 prices, the additional expenditure is already around UGX 400 bn a month. That means by December-January it will be around UGX 500bn.
This extra cost is means households still have less to spend elsewhere like in school fees and health care emergencies. Businesses too will absorb the cost in margins, postpone investment or increase prices. A refinery at home makes a big difference even if compared to the export value of Pearl Sweet when it starts earning. Uganda imports nearly 2.96 bn litres of petroleum products a year, around 18.6 mn barrels. At that volume, every $10 a barrel of refining, freight, insurance and logistics cost that could economically be avoided through domestic refining (worth close to UGX 700bn a year. At $20 it approaches Ush1.4tn).
Anyways, so much ink has been spilt on the benefits of a local refinery. Countries like Senegal with a small domestic refining capacity are a live example of what it means when a crisis like that in the Gulf completes upsets the usual. A refinery in Hoima has its own considerable capital and operating costs but the long-term benefits are obvious. In some instances, in ways that are peculiar to Uganda.
Consider that our situation (with high prices) now has to contend with a disruptive severe weather season. The official September-to-December outlook expects El Nino to intensify with Buliisa, Hoima and Kikuube are among the districts forecast to receive above-normal rainfall, particularly in late October and November extending into January. Rain may not disrupt final preparations to the oil projects, but they have caused inconveniences in the past.
Around the country food supply will be the main concern with excessive rain causing waterlogging in fields, destroying crops, increasing the likelihood of disease and spoiled produce that cannot be dried. Our roads and bridges are also exposed just like the last El Nino a factor that overlaps almost exactly with the forecast peak in diesel. Farmers may lose part of their harvest and then pay more to take what remains to market. Construction experiences the same pressure when earthworks stop, access roads deteriorate and cement, steel and machinery cost more to deliver.
I checked with the Ministry of Water and Environment about the wider hydrology (Eng. Dominic Mucunguzi kindly shared some papers on the hydrology of Lake Victoria, thank you). It shows for example that historically Lake Victoria (Nalubaale) is sensitive to direct rainfall ( this is its main source of water) while some of the effects of disruption from the wider catchment arrives with a lag of one to two years. In short even if El Nino ends when it does, some of the disruption will linger around for longer. I learnt that the 1997 El Nino was followed by a major Lake Victoria level pulse in 1998-99. During the 2019-20 wet episode Lake Victoria rose by about 1.4 metres. Large stretches of the shoreline are flat, so a relatively small vertical rise can spread water across a much larger area.
Flooding preparedness will cost billions more of scarce funds.
Energy, fuel and utilities inflation was already 14.3 per cent in August. It looks like headline inflation has a 70 per cent probability of exceeding the Bank of Uganda’s 5 per cent target by the end of March and a 55 per cent probability of at least one increase in the Central Bank Rate. If food output weakens and transport is disrupted while diesel costs around Ush7,000, the inflation problem becomes considerably wider.
Meanwhile the best-case long-term scenario with a refinery is still further away and unlikely to be resolved before oil starts shipping. Perhaps it is best to end with how these impacts on the national economic vision of a US$ 500 billion economy by 2040. These setbacks hurt any progress toward. Even with significant earnings from oil, growth is largely from industry, agriculture, services and trade.
All consume energy.
( we will return soon on the subject of the sad death of King Oyo Nyimba)